
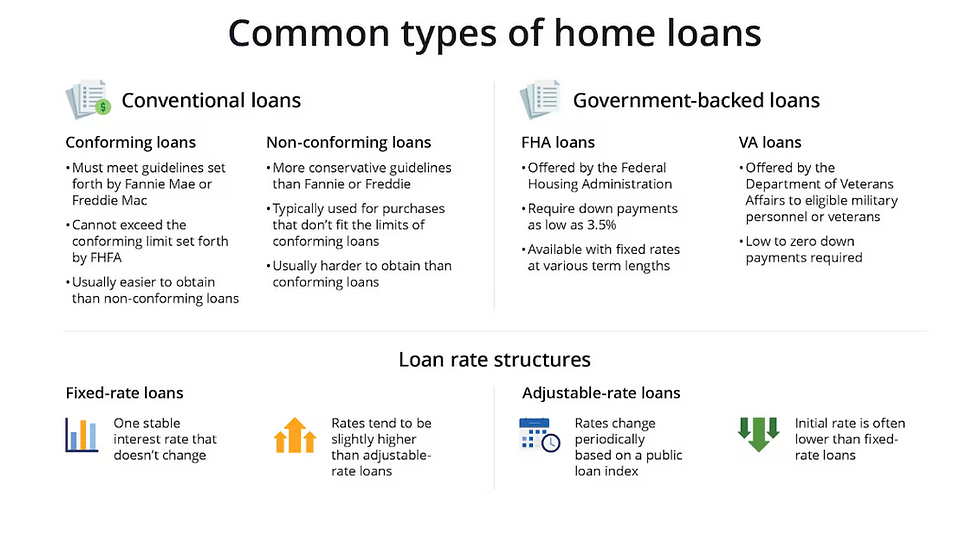
We provide guidance to the mortgage financing that best fits your goals. Home buyers come to MFD when searching for best mortgages, creative and suitable financing. Home buyers and investors know we deliver results for personal and business growth - from Conventional, FHA, VA to Jumbo Loans, and builder projects.
Exclusive Pricing Incentives
Conventional In partnership with the #1 wholesale lenders in the country, nobody does conventional loans like our partners. We combine competitive rates, groundbreaking tools and technology, and a fast, easy process to help you deliver a worry-free mortgage experience.
Conventional Cash-Out 90 A cash-out refinance option up to 89.99% LTV with a simplified process and a competitive interest rate — all without the addition of mortgage insurance.
Elite The obvious choice for your top-tier borrowers! Comprised of some of the best conventional rates and pricing in the industry, UWM's Elite program allows you to close quickly, while generating solid referrals.
Ground-up Construction Loans
financing structured to your unique needs with flexibility and an unwavering commitment to service.
Elite MI Elite MI combines competitive lender-paid mortgage insurance and borrower-paid pricing, which means you only have to go one place to deliver a lower payment for your 620+ FICO borrowers.
High Balance Time is of the essence with every borrower. Don’t wait while your borrower shops around—give them competitive rates and close their high balance loan with incredible speed!

Elite High Balance Elite High Balance offers some of the best conventional high balance rates and pricing for your top-tier clients. You'll receive industry-leading turn times, direct access to underwriting and award-winning technology with every loan.
Flexible fix and flip loans structures optimized for your residential investments.
HomeOne Qualify more first-time homebuyers with this 3% down payment solution. CLTV must be between 95.01-97% if not a community second; between 95.01-105% if it is a community second No income restrictions Available in all geographic locations Eligible for single family homes, including townhouses and condos At least one borrower must be a first-time homebuyer LPA only 95% minimum LTV Temporary Rate Buydowns available *Applicable in New York only.
Refi Possible Refi Possible helps your borrowers who currently have a Freddie Mac-backed loan save on their monthly mortgage payment. As with Fannie Mae’s RefiNow, applicants must have income at or below 100% of their area median income (AMI) and be able to reduce their interest rate by a minimum of 50 basis points. Applicable in New York Only.
RefiNow RefiNow lets more of your borrowers save on their monthly mortgage payments! Use it to help your homeowners who currently have a Fannie Mae-backed loan, have income at or below 100% of their area median income (AMI) limit, and can reduce their interest rate by a minimum of 50 basis points. Loan must be conventional and owned or securitized by Fannie Mae Must have a reduction in their monthly mortgage payment* 30-year fixed loans with an LTV up to 97% †Applicable in New York Only.
Limited Review Condos MFD makes condo approvals quick and easy with our limited review process. All files receiving a limited review response in AUS will only need a minimum evaluation by our condo department. Available in all 50 states No condo questionnaire required Lender and seller paid Temporary Rate Buydowns available
Single Premium MI Single Premium MI allows a one-time, upfront MI premium to eliminate the monthly MI payment, while ensuring the maximum credit to offset the closing fees. Strengthen your purchase business by giving your borrower the best of both worlds. Both financed and non-financed options available Down payment as low as 3% Use seller contributions to eliminate monthly MI Accommodate a low rate and payment while providing a premium credit to negate closing costs Empower your clients to qualify for the home of their dreams
Split 50 and Split 100 Split 50 and Split 100 is a hybrid program combining a single-premium M.I. adjustment with the balance of the M.I. premium to be paid at a reduced monthly rate. LTV's up to 95% Split 50 at only 50 basis points Split 100 is another option for your borrower than FHA loans Underwrite to AUS findings
Texas 50 (a)(6) Cash in with MFD's Texas 50 (a)(6) product! MFD closes Texas loans with incredible speed. Available on single- and multi-wide manufactured homes, condos and PUDs Hassle-free with MFD’s direct communication and fast turn times
HomeReady Conventional options for borrowers looking to purchase with a low down payment or refinance with limited equity. Use the Fannie Mae Lookup Tool to see the subject property’s Area Median Income (AMI). Purchases up to 97% including FTHB Refinances serviced by FNMA eligible up to 97% LTV Reduced Mortgage Insurance High Balance available Gift funds eligible for entire down payment Available on single- and multi-wide manufactured homes with LTV up to 95%, condos, co-ops* and PUDs Temporary Rate Buydowns available Income up to 80% of the AMI. First time homebuyers at or below 50% of the AMI receive a $2,500 pricing incentive *Applicable in New York only.
Home Possible A great alternative to FHA financing for borrowers looking to purchase with a low down payment or refinance with limited equity. Use the Freddie Mac Lookup Tool to see the subject property’s Area Median Income (AMI). Up to 97% LTV 620+ FICO First time homebuyers, move-up borrowers and retirees Refinances up to 97% LTV, regardless of current mortgage program Available on single- and multi-wide manufactured homes, co-ops*, condos and PUDs Temporary Rate Buydowns available Income up to 80% of the AMI. First time homebuyers at or below 50% of the AMI receive a $2,500 pricing incentive *Applicable in New York Only.
Which Mortgage is Right for You
There are a number of different types of home loans available to you, and it can pay to familiarize yourself with them. Luckily we’re here to help you choose the best type of home loan for your needs.

Fixed Rate The most common type of loan option, the traditional fixed-rate mortgage includes monthly principal and interest payments which never change during the loan’s lifetime.

Adjustable Rate Mortgages (ARM)s are loans whose interest rate can vary during the loan's term. These loans usually have a fixed interest rate for an initial period of time and then can adjust based on current market conditions. The initial rate on an ARM is lower than on a fixed rate mortgage which allows you to afford and hence purchase a more expensive home. Adjustable rate mortgages are usually amortized over a period of 30 years with the initial rate being fixed for anywhere from 1 month to 10 years. All ARM loans have a "margin" plus an "index." Margins on loans typically range from 1.75% to 3.5% depending on the index and the amount financed in relation to the property value. The index is the financial instrument that the ARM loan is tied to such as: 1-Year Treasury Security, LIBOR (London Interbank Offered Rate), Prime, 6-Month Certificate of Deposit (CD) and the 11th District Cost of Funds (COFI).

Interest Only Mortgages A mortgage is called “Interest Only” when its monthly payment does not include the repayment of principal for a certain period of time. Interest Only loans are offered on fixed rate or adjustable rate mortgages as wells as on option ARMs. At the end of the interest only period, the loan becomes fully amortized, thus resulting in greatly increased monthly payments. The new payment will be larger than it would have been if it had been fully amortizing from the beginning. The longer the interest only period, the larger the new payment will be when the interest only period ends. You won't build equity during the interest-only term, but it could help you close on the home you want instead of settling for the home you can afford.
Graduated Payment Mortgages A graduated payment mortgage is a loan where the payment increases each year for a predetermined amount of time (such as 5 or 10 years), then becomes fixed for the remaining duration of the loan. When interest rates are high, borrowers can use a graduated payment mortgage to increase their chances of qualifying for the loan because the initial payment is less. The downside of opting for an smaller initial payment is that the interest owed increases and the payment shortfall from the initial years of the loan is then added on to the loan, potentially leading to a situation called "negative amortization." Negative amortization occurs when the loan payment for any period is less than the interest charged over that period, resulting in an increase in the outstanding balance of the loan.
Flexible fix and flip Property Types
Single-Family, Multi-Family (2–20 units), Townhomes, Condos, Planned Unit Developments (PUD).
Ground-up Construction Loans
financing structured to your unique needs with flexibility and an unwavering commitment to service.

Customized commercial real estate financing solutions to expand what’s possible.

Working with you every step of the way—from ideation to execution—Mortgage First Direct leverages unparalleled expertise, deep relationships with capital sources, and an unwavering commitment to your success to help you confidently navigate the complexity of the capital markets in financing commercial real estate projects.