Apply for a mortgage and
start your journey
-
Get started with no impact to credit score
-
Closing cost and downpayment assistance
-
Shop for homes with a Mortgage First Direct preapproval

See how much home you can afford
Our affordability calculator overlay estimates your maximum home price and monthly mortgage payment. Some loans offer down payments as low as 3% .

How to start a mortgage application
1
Start a mortgage preapproval
Answer a few questions about yourself, your mortgage needs and your finances.
2
Connect with an HLA
We’ll connect you with a Home Lending advisor to review your mortgage preapproval and guide you through the next steps.
3
Start making offers on homes
Once you have a mortgage preapproval letter, you’ll show sellers you’re a serious buyer.
To get a preapproval letter, begin by starting an application. We’ll ask for information from you and any co-applicants you may have. Once you submit your application, we’ll connect you with a Home Lending Advisor who can help you choose a loan option that works for you. Then, if you’re eligible, you’ll get a preapproval letter based on income and asset information you provide to show real estate agents and sellers that you can secure a mortgage. It doesn’t guarantee that your loan will be approved, but it shows you’re a serious homebuyer while you’re shopping for homes.
We’ll ask you for details like your homebuying goals, contact info, employment and assets. We’ll also need to know if you have a co-applicant and if you have any properties already. When you submit your application, we’ll connect you with a Home Lending Advisor. They’ll help you with your loan details, run a credit check for you and help you prepare for closing. Whether you’re buying your first home, your next home or an investment property, we offer guidance for each stage of buying a home.
Do you offer financial assistance? Yes, for eligible primary residences in select areas,
We’ll tell you exactly what you’ll need to provide after you submit your application, but here are some documents we typically ask for:
-
Pay stubs for the last 2 months
-
W-2 forms for the last 2 years
-
Bank statements for the last 2 or 3 months
-
Federal tax returns for the last 1 or 2 years
-
Info on current debt, including car loans, student loans and credit cards
-
Proof of homeowner’s insurance

How Much House Can You Afford?

Home Purchase Loans from Mortgage First Direct
Buying a home is one of the biggest financial decisions you’ll ever make — and choosing the right mortgage lender can make all the difference. At Mortgage First Direct, we specialize in home purchase loans designed to help buyers succeed in today’s competitive real estate market and into 2026. Whether you’re a first-time buyer or a repeat homeowner, we provide the strategy, speed, and flexibility needed to win the home you want.
A Smarter Way to Buy a Home
Find the mortgage that best fits your goals. Home buyers come to us when searching for best mortgage lenders for home buyers - and they stay because we deliver results - from Conventional, FHA, VA to Jumbo Loans.
Our Fast Pre-Approvals Give You an Advantage

Buying a house for the first time is an exciting milestone! Whether you want to stop renting, relocate, or expand your family, we’re here to help you on your homebuying journey.
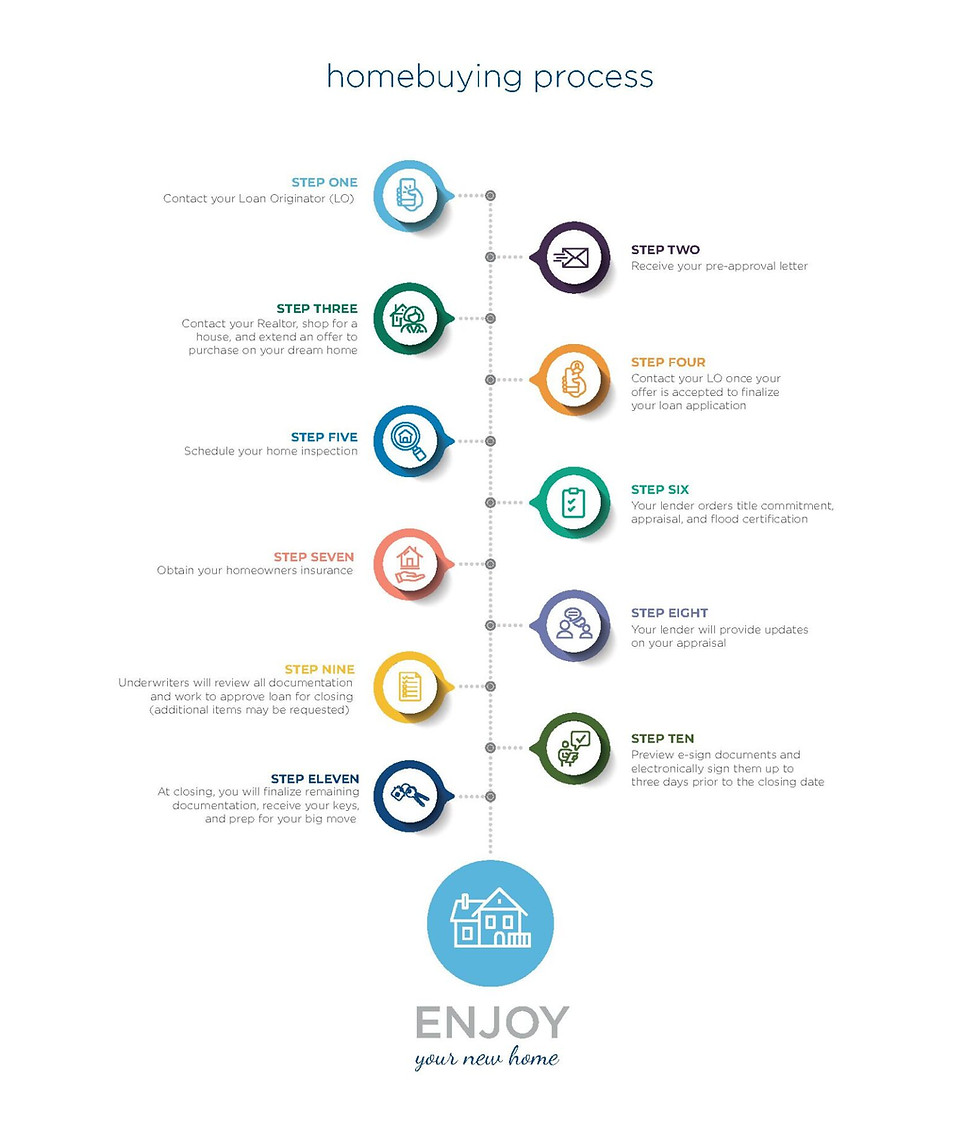
This step-by-step guide sheds light on the homebuying process and includes valuable tips and tricks to help you along the way. It’ll help you understand what a typical home purchase looks like from start to finish.
Remember that every homebuyer’s journey is different. Yours might be slower or faster depending on a wide range of factors.
Ready to get started? Let’s dive in.
Steps to buying a house
-
Deciding if buying a home is right for you (6-12 months out)
-
Determining your budget for a down payment (6-9 months out)
-
Getting pre-qualified/pre-approved for a mortgage (3 months out)
-
Finding your home (2-3 months out)
-
Making an offer (2 months out)
-
Preparing to close on your home (1 month out)
-
Getting ready for closing day (1-2 weeks out)
-
Final thoughts on how to buy a house

first responder loans

low interest rate
Multi-unit Buildings

investment property

closing cost & title
DRINK
Consider market conditions
When you're buying a home, it can be helpful to understand what's going on in the real estate market. Conditions in the housing market can affect how long it takes you to find a home and the final price you pay.
Depending on the supply and demand of homes, the market may favor either buyers or sellers.